


Section 232 tariffs are additional U.S. import duties imposed on designated products when imports are determined to threaten national security under the Trade Expansion Act of 1962. Importers determine their exposure by identifying the correct Harmonized Tariff Schedule (HTS) classification, checking applicable Chapter 99 provisions, and verifying the duty rate, effective date, and available exceptions. The total duty depends on the imported product, country of origin, and other applicable trade measures.
What Are Section 232 Tariffs?
Under Section 232 of the Trade Expansion Act of 1962, the U.S. Department of Commerce investigates whether imports threaten to impair national security. Following the investigation, the President determines whether to take action, which may include imposing additional duties, adjusting import quantities, or adopting other measures authorized by the statute.
After the investigation, if the President decides to apply tariffs in response to a national security threat under Section 232, it is the responsibility of U.S. Customs and Border Protection (CBP) to collect those additional duties from importers.
Section 232 tariffs are separate and distinct from tariffs levied under Section 301 of the Trade Act of 1974 and anti dumping/countervailing duties (AD/CVDs).
Which Commodities Are Subject to Section 232 Tariffs?
Section 232 tariffs apply to the following imported goods. Except where mitigated by a trade act such as the United States-Mexico-Canada Agreement (USMCA), U.S.-Japan Agreement, or U.S.-UK Economic Prosperity Deal, the rates are consistent regardless of country of origin.
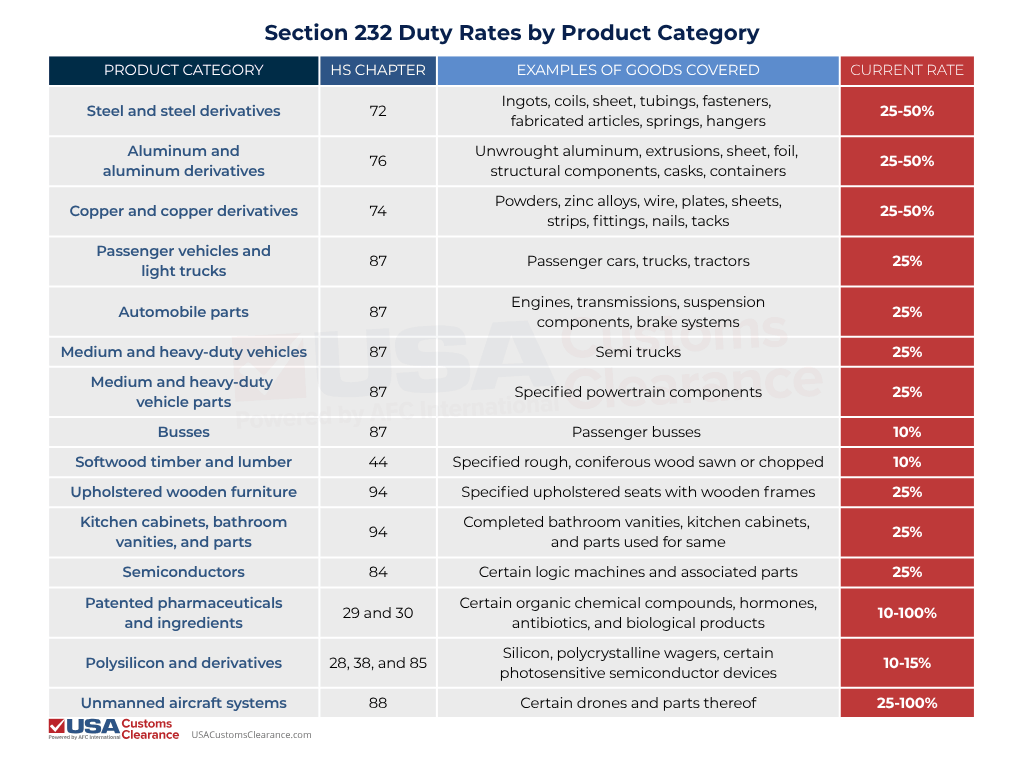
These rates are current as of November 4, 2026, and tariffs on affected wood products are scheduled to increase in January 2027 per presidential proclamation. Importers must also be aware of Section 301 tariffs, which aren’t the same as these commodity-specific additional duties.
What Is the Difference Between Section 232 and Section 301 Tariffs?
Where Section 232 tariffs are assessed against specific goods without regard to country of origin (unless otherwise specified or reduced/mitigated by a trade act), Section 301 tariffs derived from the Trade Act of 1974 apply to goods from specific countries.
For example, a presidential memorandum dated July 23, 2026, applied tariffs of 10 to 12.5% on goods imported from 60 trade partners due to the “failure of each economy to impose and effectively enforce a prohibition on the importation of goods produced with forced labor.” This is a typical application of Section 301 as it is levied per economy, not per commodity.
Official guidance from CBP asserts that, unless mitigated by a trade agreement, these tariffs can stack with one another. For instance, an importer bringing in $100,000 worth of goods from China affected by a 25% Section 232 tariff and a 25% Section 301 tariff would be responsible for $50,000 ($25,000 per assessed tariff) in duties before incorporating the appropriate column duty from the HTS.
How Can Importers Determine Whether Section 232 Applies?
Importers can determine whether Section 232 duties apply by verifying their products’ HTS classifications against the relevant government annexes and Chapter 99 provisions. They must also confirm the applicable tariff rate, entry date, country-specific treatment, and any available exclusions before calculating the additional duty.
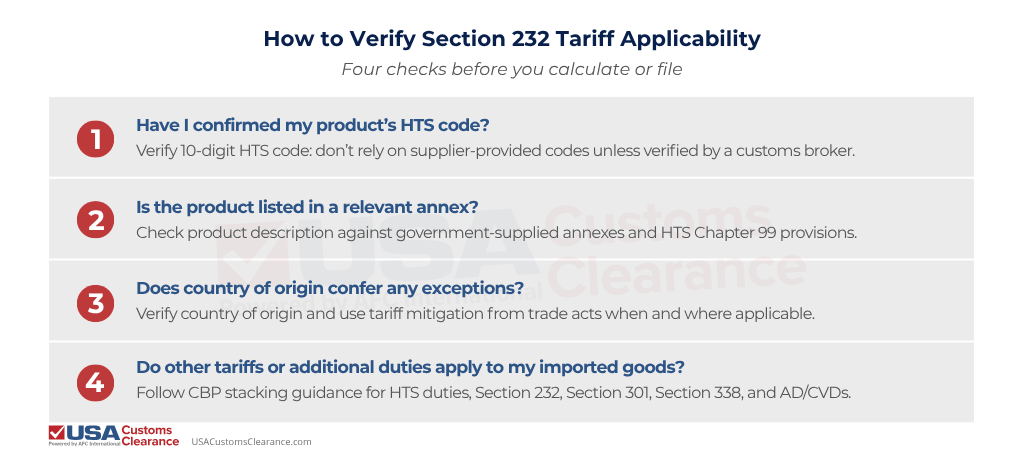
As mentioned above, determining which tariffs apply to a shipment is best done with the assistance of a licensed customs broker, especially when multiple additional duties can apply.
How Are Section 232 Tariffs Calculated?
Section 232 tariffs are calculated as a percentage of the value of the imported goods affected by the additional duty. This is called an ad valorem assessment. We can use two sample calculations to show how to perform this calculation: one for an article composed entirely of steel, and another for a partially-steel commodity.
Sample Section 232 Tariff Calculation: Steel Ingots
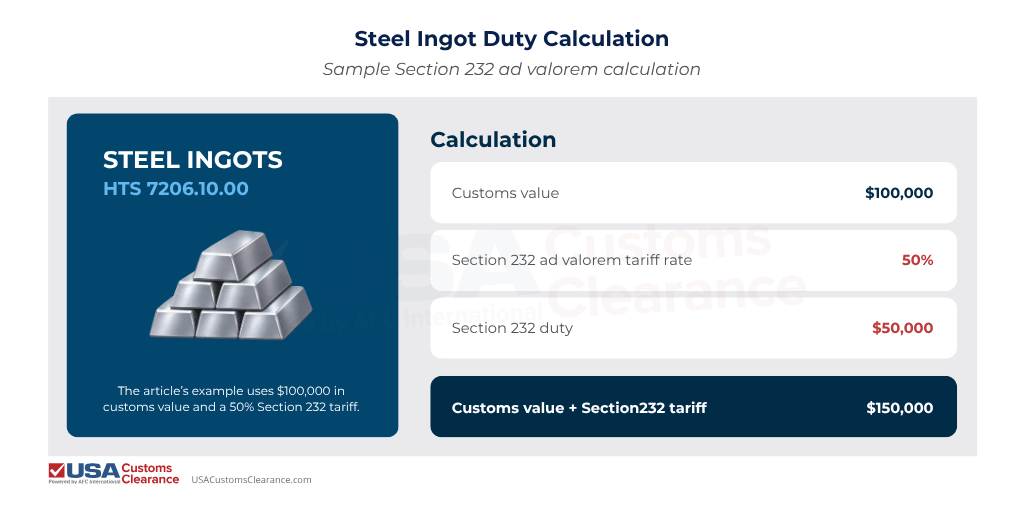
An importer orders $100,000 of steel ingots (HTS code 7206.10.00.) from Mexico. The chapter and subheading, 7206, are subject to a 50% Section 232 tariff, while the column duty for this particular commodity is free.
Since 50% of $100,000 is $50,000, the importer will be responsible for $50,000 in duties under Section 232.
For a partially metal commodity, let’s say that same instead orders $100,000 worth of portable, gas-powered cooking appliances covered under HTS code 7321.11.10. These goods are subject to a 25% Section 232 tariff on their full value, plus a 5.7% rate of duty from the HTS.
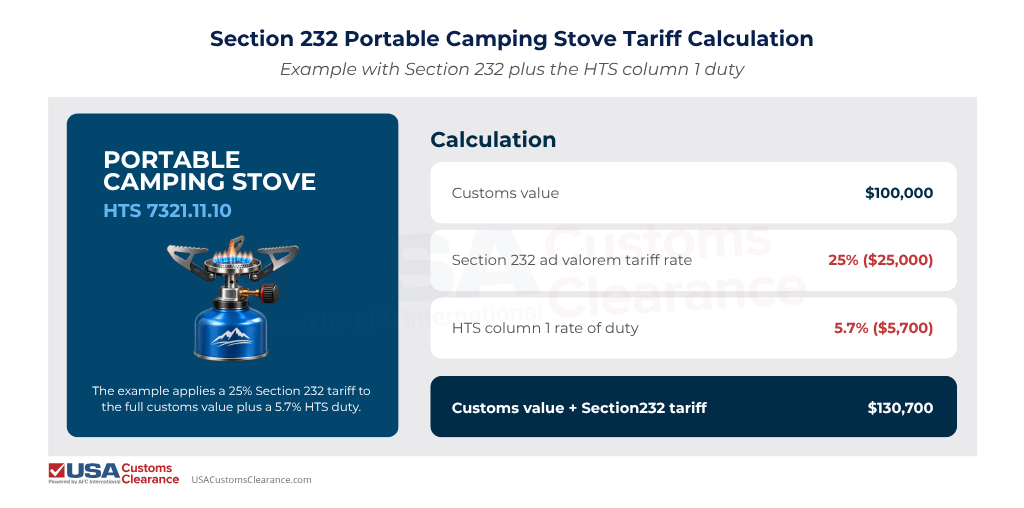
These calculations are for illustrative purposes and do not take into account other additional duties that may also stack with Section 232.
Do Section 232 Tariffs Stack With Other Import Duties?
Yes, Section 232 duties usually stack with HTS duties and can stack with tariffs under Section 301, Section 338 of the Smoot-Hawley Tariff Act of 1930, and AD/CVDs. It’s common for importers to assume only one tariff applies to their goods, which leads to compliance failures and triggers delays at customs clearance.
What Are the Most Common Section 232 Compliance Mistakes?
In addition to incorrectly assuming that multiple tariffs don’t stack, importers often make the following mistakes with regard to Section 232’s applicability to their goods:
- Using the wrong HTS code, leading to classification errors
- Failing to apply applicable Section 232 tariffs to goods downstream of steel, aluminum, and copper
- Assuming a trade deal mitigates or eliminates sectoral duties in addition to standard HTS duties
- Missing verification documents to back up legitimate claims of preferential tariff treatment
To fulfill CBP’s reasonable care requirements, importers must ensure the information they present to the agency isn’t just accurate, but verifiable.
How Can a Customs Broker Help With Section 232 Compliance?
A licensed customs broker has the education, licensure, and ongoing training required to fully understand and correctly apply Section 232 tariffs. Since importers are necessarily focused on building their businesses, partnering with a customs broker is vital to making sure CBP’s requirements regarding accurate HTS classification, remittance of duties, and compliance with applicable regulations from Partner Government Agencies aren’t overlooked.
If you have questions or would like to set up a consultation with one of our licensed customs brokers, contact us at (855) 912-0406.
 Copy URL to Clipboard

Did you find this article helpful?
See more of our coverage on Google.
Add usacustomsclearance.com as a preferred source!

Add usacustomclearance.com as a preferred source!
See more of our coverage in Google's Top Stories.
Add your first comment to this post