

Duty drawback is a refund program that allows importers to recover up to 99% of duties paid on goods that are later exported or destroyed. This guide explains eligibility, required documents, timelines, and common filing mistakes.
What is Duty Drawback?
Duty drawback is a U.S. Customs and Border Protection (CBP) program that refunds up to 99% of import duties when goods are exported or destroyed, provided the importer meets documentation and eligibility requirements.
According to the CBP, the agency collects import duties and refunds eligible amounts through the drawback program. These fees are:
- Duties
- Tariffs, including Section 301 tariffs
- Taxes
- Miscellaneous Fees like the CBP Harbor Maintenance Fee (HMF) or Merchandise Processing Fee (MPF)
The only fees eligible for drawback are customs fees payable to CBP, not customs brokerage, warehouse, or freight transportation fees.
We’ve illustrated what a typical duty drawback scenario looks like in the chart below:
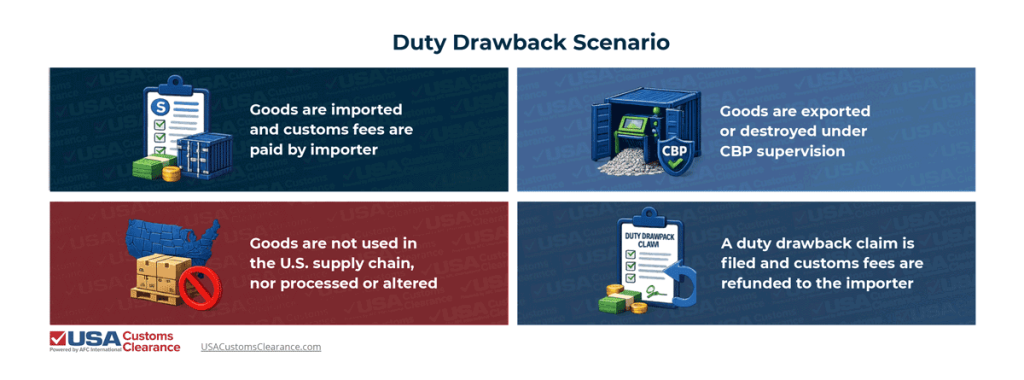
While duty drawback refunds are up to 99%, there are exclusions to what claims qualify. We’ll go over what criteria CBP verifies to accept a drawback claim.
Which Imports Qualify for Duty Drawback Refunds?
Imports may qualify for duty drawback if they are exported, destroyed, or used in manufacturing exported goods. Eligibility depends on the drawback type, product classification, and whether the importer can prove compliance with substitution or unused merchandise requirements.
Re-Exported Merchandise
Re-exported merchandise refers to goods imported to the U.S. and subsequently exported to another country without undergoing significant alteration or manufacturing transformation.
Merchandise is exported for reasons such as:
- Merchandise contributed to inventory overstock and increased warehousing fees
- Merchandise included the wrong items and was returned to supplier
- Merchandise was discovered to be damaged/defective after inspection at no fault of the shipper
When merchandise is unused, rejected, and re-exported, importers may be eligible for a duty drawback.
Destroyed Merchandise
Destroyed merchandise is an imported product that is destroyed under CBP supervision instead of being exported from the United States.
Merchandise is destroyed for reasons similar to exported merchandise, but also include:
- Damaged or defective goods
- Expired goods
CBP may not always be present to witness the destruction of goods. To qualify for drawback, importers must submit CBP Form 7553 (Notice of Intent to Export, Destroy, or Return Merchandise) when merchandise is destroyed.
In the next section, we’ll discuss more of the CBP documentation and data required to file your refund.
What Documents Are Required for A Duty Drawback Claim
Importers will need to gather the following federal forms and data to file a drawback claim with CBP.
- CBP Form 7501 entry summary
- CBP Form 7551 drawback entry
- CBP Form 7553 notice of intent for drawback purposes
While these forms can be filed as paperwork, CBP requires most customs documentation to be electronically submitted and managed through its Automated Commercial Environment (ACE) via the Automated Broker Interface (ABI). The Automated Commercial Environment (ACE) is CBP’s digital platform for filing and managing customs transactions. Through ABI, a paper CBP Form 7551 is not required.
Let’s look at the information you’ll need to file your drawback.
Entry Data Elements
Drawback claims require the following information that’s found on your specific CBP entry type.
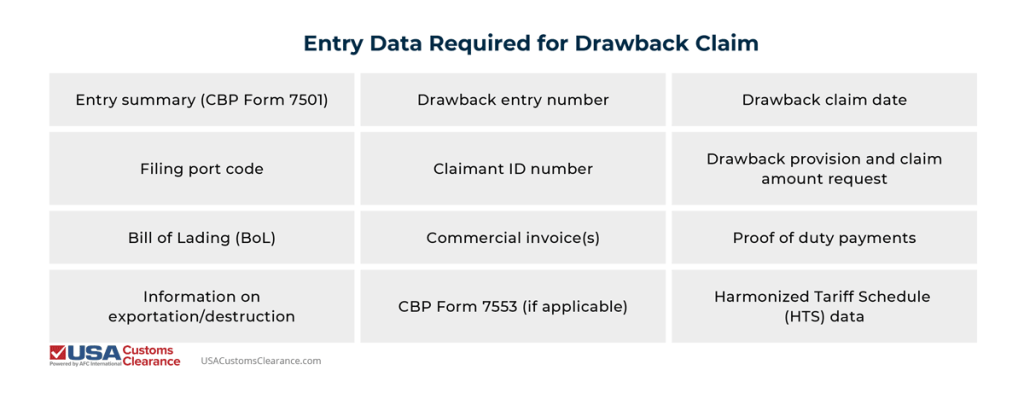
Importers can use this information to request the following types of drawback:
- Manufacturing Drawback: A manufacturing drawback is a refund for imported goods used to manufacture products that were exported or destroyed at a later date.
- Unused Merchandise Drawback: An unused merchandise drawback is a refund for imported goods that were never used in the U.S. and later destroyed or exported.
- Rejected Merchandise Drawback: A rejected merchandise drawback is a refund for imported goods that are defective or shipped without the importer/consignee’s consent and later destroyed or exported.
- Destruction Drawback: A destruction drawback is a refund for unsafe or defective imported goods that are destroyed under CBP supervision.
Let’s move on to the data you’ll need for exportation proof.
Export Proof
When importers must export their goods and file for a refund on importing fees, CBP requires the following information to prove the products have been exported:
- Export receiving country
- Export date
- Exporter name
- Description of products
- Quantity and unit of measure
- Export number (Schedule B)
Exporters should have their CBP entry number and correct Schedule B number to support a drawback claim.
In the next section, we’ll discuss how to use this information to start the duty drawback claim process and monitor the expected CBP timeframes for compensation.
How Does the Filing Process Work?
The filing process involves identifying eligible transactions, selecting the correct drawback provision, compiling required documentation, and submitting the claim to CBP. Claims are reviewed and refunds are issued after approval or earlier under Accelerated Payment privileges (AP) according to the 19 CFR (Code of Federal Regulations) § 192.92.
In the following sections, we’ll break down how the typical duty drawback claim process works.
1. Identify Candidates
A duty drawback candidate is an individual who is listed as the drawback claimant. The candidate can be the importer, exporter, or manufacturer who is filing for drawback.
2. Compile Documents
Once the candidate has been identified, they must compile the CBP-required documents to file, such as their entry summary, commercial invoice, BoL, export proof, if applicable, and other shipping papers.
3. File Duty Drawback
The candidate must file their duty drawback through ABI. Use the following steps to file a claim on ACE in one of three ways:
- Self-file claim through ABI
- Hire a Licensed Customs Broker to file the claim
- Use a service provider, like a duty drawback specialist, to file
Self-file claimants must purchase software to establish an ABI communication link with the CBP to file and manage their claim in ABI.
4. Follow-Up
CBP will follow up with claimants if their duty drawback claim has been accepted or denied through the ACE portal. According to 19 CFR (Code of Federal Regulations) § 163.4, claimants must keep duty drawback records for up to three years after the date the duty drawback was refunded.
The duty drawback can be complex, but partnering with a Duty Drawback Broker can help smoothen the process and secure your refund sooner.
What Is the Timeline for Duty Drawback Claims?
The timeline for duty drawback claims can vary between standard claims and Accelerated Payment privilege (AP). The AP is a program offered by CBP that allows importers to receive duty drawback refunds within a few weeks.
We’ve provided a graphic showing the difference in timelines for standard and AP claims.
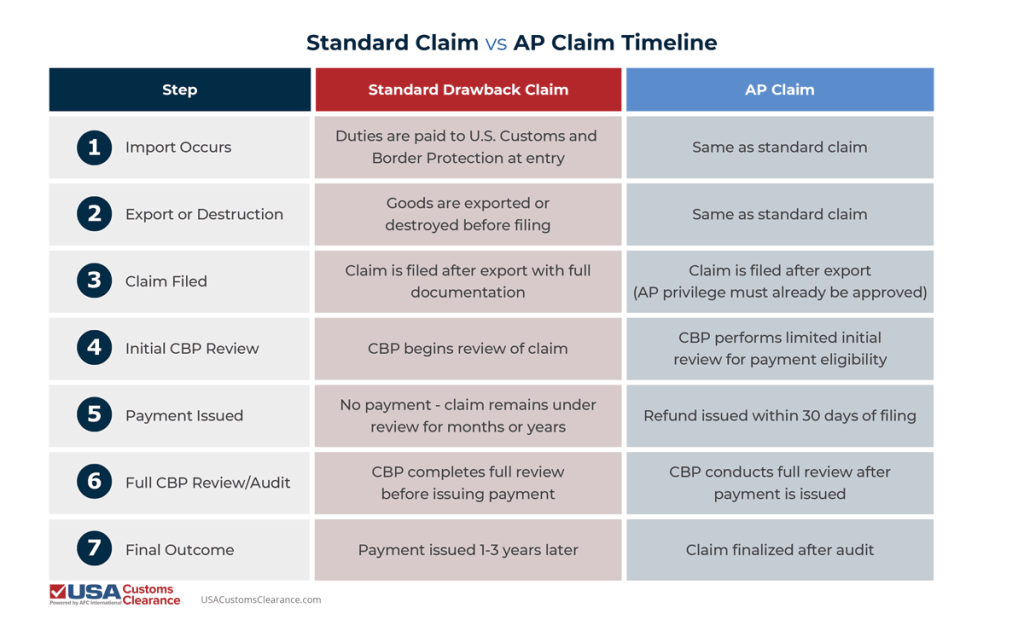
As the table shows, the AP privilege program is your best option for obtaining your drawback refund in a timely manner.
Why Do Duty Drawback Claims Get Denied?
Duty drawback claims fail when importers cannot prove a clear link between imported and exported goods, submit incomplete documentation, or apply the wrong drawback provision. CBP also denies claims for classification errors and missed deadlines.
Now that you have a qualification checklist, you’re able to navigate these pitfalls and file your duty drawback to recoup customs fees losses.
Successful Claims vs Failed Claims
To illustrate what a successful and failed duty drawback claims look like, we’ll go through one example of each.
First, we’ll start with a successful claim:
A U.S.-based importer brings in 10,000 stainless steel water bottles from China. At entry, they pay $25,000 in import duties to CBP. Rather than selling all of them in the U.S., they sell 6,000 of the bottles to a buyer in Canada. The importer files a duty drawback claim for the 6,000 unused bottles.
Their claim is successful for the following reasons:
- Clear Audit Trail: Import and export records matched.
- Timely Filing: Claim submitted within a 5-year statutory window.
- Accurate Classification: Same Harmonized Tariff Schedule (HTS)-classification for import/export.
- No Prior Use: Goods remained unused before export.
Now, let’s take a look at an unsuccessful claim:
A U.S. apparel company imports 8,000 cotton t-shirts from India and pays $18,000 in duties to CBP. The company later exports 5,000 of cotton-poly blend t-shirts to the UK and files a substitution unused merchandise drawback claim.
Their claim is unsuccessful for the following reasons:
- Non-matching HTS classification: Imported shirts were classified under a different HTS code than the exported shirts.
- Material Differences In the Product: The imported shirts were 100% cotton, while exported shirts were made from a cotton-poly blend.
The takeaway from these examples is to ensure your HTS classification is accurate, that you're exporting or destroying the same items you import, and that you file your claim within the required timeframe.
Who Should File A Duty Drawback Claim?
There are two people that can file your drawback claim: yourself or your customs broker. Ideally, your customs broker should file the claim on your behalf. If managing documentation, timelines, and compliance requirements feels overwhelming, many importers work with licensed drawback specialists to reduce errors and accelerate refunds.
USA Customs Clearance: Your Preferred Customs Broker
If you need help with duty drawback, USA Customs Clearance can help. Our Licensed Customs Brokers will help get the refund for your exported or destroyed goods. Navigate to our service page and choose the service that’s best for you. If you have any questions, call us at (866) 763-6859 or contact us.
FAQ
What is a duty drawback?
A duty drawback is a refund shippers receive for paid duties on a shipment that was exported or destroyed.
How long does it take to receive my duty drawback refund?
The duty drawback claim process can take up to six months or longer depending on the complexity of your entry. CBP typically issues a refund check between 30 to 60 days after drawback entry liquidation.
Where do I file my CBP duty drawback claim?
Shippers can file their drawback electronically through CBP’s Automated Commercial Environment (ACE) via the Automated Broker Interface (ABI) system. Self-filing shippers must purchase a special software to establish an ABI communication link with CBP prior to filing.
Sources:
New IEEPA Duty Refunds Webpage, U.S. Customs and Border Protection, 2026
Drawback, U.S. Customs and Border Protection, 2025
CBP Form 7501: Entry Summary, U.S. Customs and Border Protection, 2026
CBP Form 7553 - Notice of Intent to Export, Destroy or Return Merchandise or Return Merchandise for Purposes of Drawback, U.S. Customs and Border Protection, 2025
Schedule B/Export Number, U.S. Customs and Border Protection, 2026
Title 19, Chapter 1, Part 163 Record Retention Period, Code of Federal Regulations, 2026
Title 19, Chapter 1, Part 191, Subpart I 191.92 Accelerated Payment, Code of Federal Regulations, 2026
 Copy URL to Clipboard

Did you find this article helpful?
See more of our coverage on Google.
Add usacustomsclearance.com as a preferred source!

Add usacustomclearance.com as a preferred source!
See more of our coverage in Google's Top Stories.
Add your first comment to this post